Bid-to-Actual Analysis: How to Know Whether Your Tender Business Is Really Profitable
A tender has been awarded.
The goods have been delivered.
The customer has accepted the order.
The invoice has been issued.
The payment has been collected.
The project is closed.
So, was it successful?
Most companies would look at the sales value and say yes.
But sales value does not tell the whole story.
The real question is:
Did the tender perform as we expected when we decided to bid?
This is where Bid-to-Actual Analysis becomes essential.
1. The Bid Was Based on Assumptions
Every tender quotation contains assumptions.
Before submitting the bid, the company estimated:
- Supplier cost
- Freight
- Customs or other charges
- Delivery cost
- Other project costs
- Selling price
- Expected margin
- Delivery timing
- Payment timing
These numbers were estimates at the time of the bid.
After execution, the company has something much more valuable:
Actual results.
The purpose of Bid-to-Actual Analysis is to compare the two.
2. The Basic Logic Is Simple
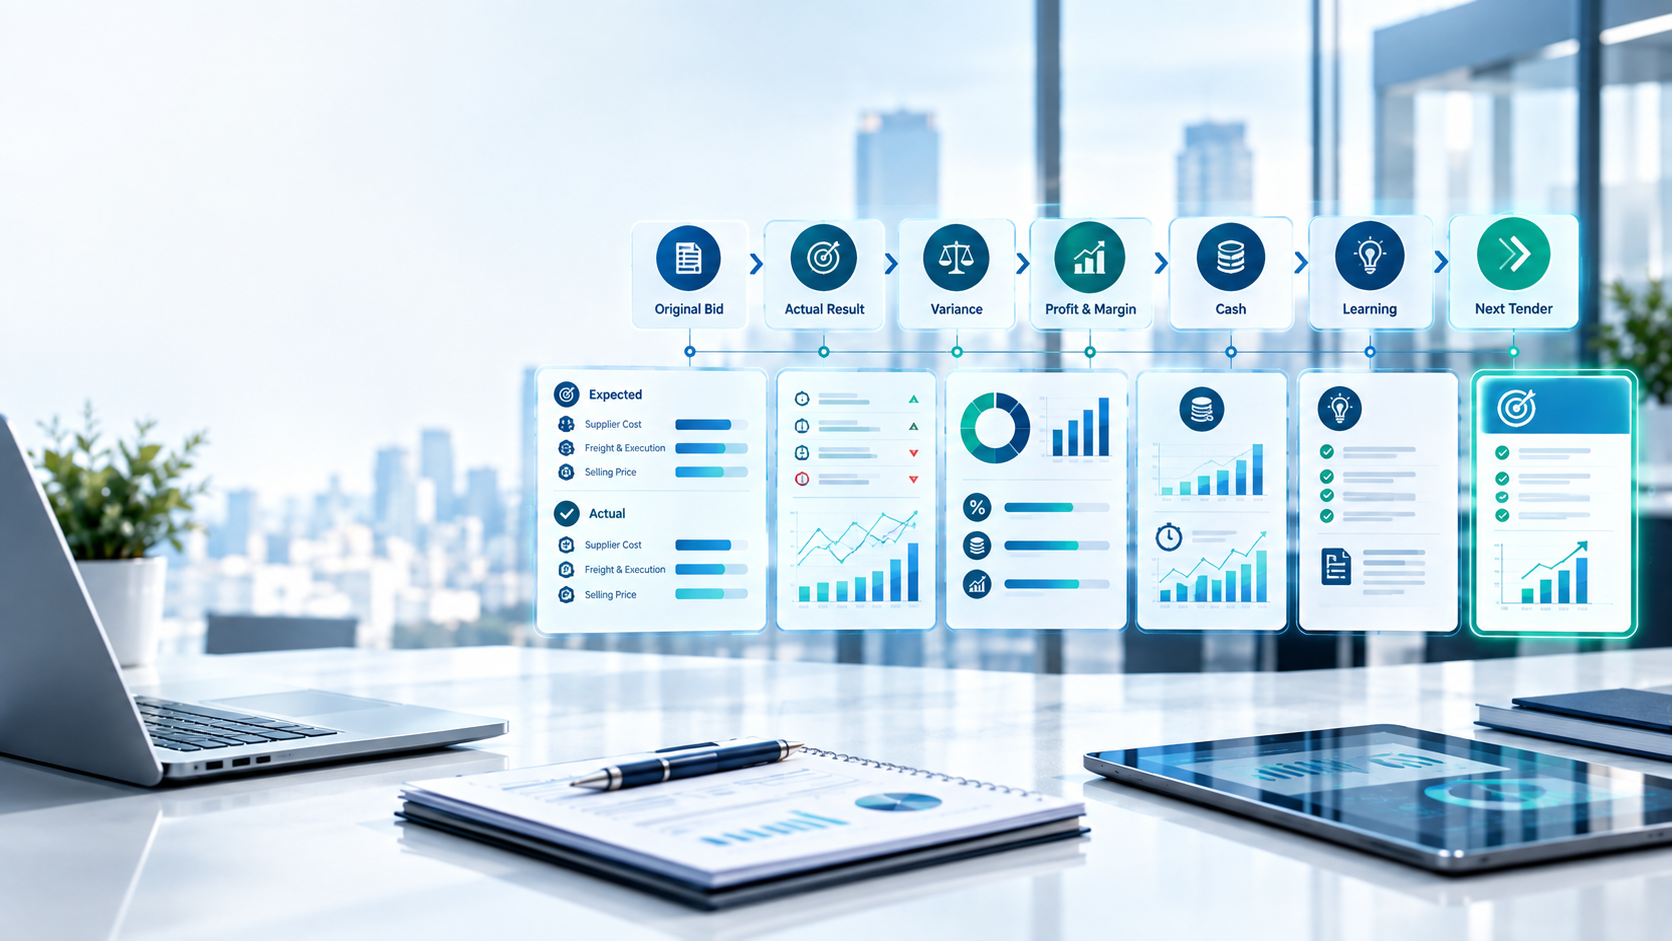
The process can be summarized as:
text id=”r5k8w2″ ORIGINAL BID │ │ ▼ EXECUTION │ ▼ ACTUAL RESULT │ ▼ BID vs. ACTUAL │ ▼ VARIANCE │ ▼ WHY? │ ▼ LESSON │ ▼ NEXT TENDER
The objective is not to produce a complicated financial report.
The objective is to answer:
What did we expect, what actually happened, and why was there a difference?
3. Start With Cost
Consider a simple tender.
Original Bid
| Item | Bid |
| Supplier cost | $100,000 |
| Freight | $4,000 |
| Other costs | $6,000 |
| Total cost | $110,000 |
| Selling price | $130,000 |
| Expected profit | $20,000 |
The tender appears attractive.
But after execution:
Actual Result
| Item | Actual |
| Supplier cost | $105,000 |
| Freight | $7,000 |
| Other costs | $7,000 |
| Total cost | $119,000 |
| Selling price | $130,000 |
| Actual profit | $11,000 |
The company still made money.
But expected profit was:
$20,000
Actual profit was:
$11,000
The company therefore lost $9,000 of expected profit during execution.
That difference deserves investigation.
4. Variance Is a Signal, Not an Explanation
Knowing that profit changed from $20,000 to $11,000 is useful.
But it is not enough.
The next question is:
Why?
The $9,000 variance may have come from several sources.
For example:
| Variance | Impact |
| Supplier price increase | -$5,000 |
| Freight increase | -$3,000 |
| Other execution cost | -$1,000 |
| Total profit variance | -$9,000 |
Now the company has information it can actually use.
It may discover that supplier price volatility was the major problem rather than pricing itself.
That distinction matters for the next tender.
5. Not Every Variance Is a Mistake
A variance does not automatically mean someone performed badly.
Some changes are outside the company’s control.
For example:
- Supplier prices changed
- Freight rates increased
- Customer requirements changed
- Exchange rates moved
- Delivery conditions changed
Other variances may be caused by internal decisions:
- Incorrect cost estimate
- Supplier selection error
- Poor negotiation
- Incomplete tender review
- Unrealistic delivery assumption
- Uncontrolled scope change
- Execution inefficiency
The objective is therefore not to find someone to blame.
It is to understand the cause of the difference.
6. Separate Estimate Problems From Execution Problems
This is one of the most useful aspects of Bid-to-Actual Analysis.
Suppose the original freight estimate was:
$4,000
Actual freight was:
$7,000
There are at least two very different possibilities.
Scenario A — Poor Estimate
The actual freight rate was predictable, but the original estimate was inaccurate.
The lesson:
Improve freight estimation.
Scenario B — Unexpected Change
The original freight estimate was realistic, but transportation costs increased unexpectedly.
The lesson may be:
Add greater protection against freight volatility.
The same variance can therefore produce completely different lessons depending on its cause.
7. Compare More Than Profit
Bid-to-Actual analysis should not focus only on financial results.
Other important comparisons include:
Cost
Bid vs. Actual Cost
Selling Price
Quoted vs. Final Contract Value
Margin
Expected vs. Actual Margin
Delivery
Promised vs. Actual Delivery Date
Supplier
Expected vs. Actual Supplier Performance
Cash
Expected vs. Actual Payment Timing
Quantity
Quoted vs. Delivered Quantity
Scope
Original vs. Actual Scope
This creates a much more complete picture of tender performance.
8. The Customer Payment Cycle Matters
Imagine that the bid assumed payment within 60 days.
Actual payment arrived after 120 days.
The project may still show the same accounting profit.
But the company’s cash was tied up for an additional two months.
For a company with limited working capital, this can materially affect its ability to pursue other opportunities.
Therefore:
Tender performance is not only about profit. It is also about cash and execution reality.
9. Supplier Performance Should Become Knowledge
Suppose Supplier A offered the lowest quotation during the tender.
The company selected Supplier A.
During execution:
- Delivery was late
- Some quantities were incorrect
- Replacement shipments were required
- Additional transportation costs occurred
The next tender should not treat Supplier A as if nothing happened.
The company’s supplier knowledge has changed.
The organization has now learned something valuable:
Supplier price is only one part of supplier performance.
That knowledge should become part of future procurement decisions.
10. Build a Tender Learning Record
A simple learning record can contain:
| Area | Bid | Actual | Variance | Lesson |
| Supplier Cost | $100k | $105k | +$5k | Reconfirm validity before bid |
| Freight | $4k | $7k | +$3k | Improve logistics estimate |
| Delivery | 30 days | 38 days | +8 days | Add supplier lead-time buffer |
| Profit | $20k | $11k | -$9k | Review margin protection |
This is much more valuable than simply recording:
Tender won: Yes
11. Turn Learning Into the Next Tender
This is where the process becomes a continuous improvement system.
Suppose the company discovers that supplier quotations frequently expire before the tender is awarded.
The next tender process could introduce:
- Shorter quotation validity assumptions
- Supplier reconfirmation before submission
- A price-adjustment risk factor
- Alternative suppliers
- Better supplier negotiation
The lesson has therefore moved from:
One completed tender
to
A better future tender process.
12. The Learning Loop
The complete OpexEdge learning loop is:
text id=”p4s6t1″ ESTIMATE │ ▼ BID │ ▼ WIN / LOSE │ ▼ EXECUTE │ ▼ ACTUAL │ ▼ VARIANCE │ ▼ ROOT CAUSE │ ▼ LESSON │ ▼ IMPROVED ESTIMATE │ └──────────────► NEXT TENDER
This is the difference between a company that simply processes tenders and a company that learns from its tender history.
13. What Management Should See
Management does not need every procurement detail from every tender.
It needs useful signals.
For example:
- Win rate
- Average expected margin
- Average actual margin
- Average margin variance
- Supplier cost variance
- Delivery variance
- Payment-delay variance
- Major recurring causes of profit erosion
Over time, patterns become visible.
Perhaps:
- Certain suppliers consistently outperform others.
- Certain product categories produce better margins.
- Certain customers have difficult payment cycles.
- Certain tender types regularly create delivery problems.
- Certain pricing assumptions are consistently optimistic.
This transforms historical tender data into commercial intelligence.
14. The Five-Article Tender Business Model
The five articles now form one connected operating cycle.
1. Tender Intelligence
Find & Screen
Question:
Is this tender worth investigating?
2. Procurement
Source & Establish Cost
Question:
What will it realistically cost us?
3. Commercial
Price & Go/No-Go
Question:
What should we charge, and is the tender worth bidding?
4. Project Execution
Deliver & Close
Question:
Can we deliver the promise while protecting the expected result?
5. Bid-to-Actual Learning
Measure & Improve
Question:
What actually happened, and what should we change next time?
Together:
text id=”c1n5x8″ FIND ↓ SCREEN ↓ SOURCE & COST ↓ PRICE & DECIDE ↓ SUBMIT ↓ WIN / LOSE ↓ EXECUTE ↓ LEARN ↓ IMPROVE NEXT TENDER
Conclusion
A tender business becomes stronger when it stops treating every tender as an isolated transaction.
Every tender contains information.
The company learns:
- Which suppliers are reliable
- Which costs are predictable
- Which assumptions are weak
- Which customers pay on time
- Which products create problems
- Which pricing strategies work
- Which risks repeatedly erode margins
The objective of Bid-to-Actual Analysis is therefore not simply to calculate the final profit.
It is to convert experience into a better decision for the next opportunity.
Estimate → Actual → Variance → Learning → Improved Estimate.
That closes the tender management loop.
And this is the real objective of the OpexEdge approach:
Do not just win more tenders. Build a tender business that gets better at winning the right tenders—and delivering them profitably.
OpexEdge Tender Business Model
Find → Screen → Source & Cost → Price & Decide → Submit → Win/Lose → Execute → Learn
A disciplined tender operation connects intelligence, procurement, commercial decision-making, execution, and learning into one continuous business process.
Related Topics
Government Tender Procurement Service | OpexEdge
Tenders Management-How to Find Reliable Suppliers and Calculate Your Real Tender Cost
Tenders Management-Tender Pricing Strategy: How to Set a Competitive Price and Decide Whether to Bid
